Executive Summary
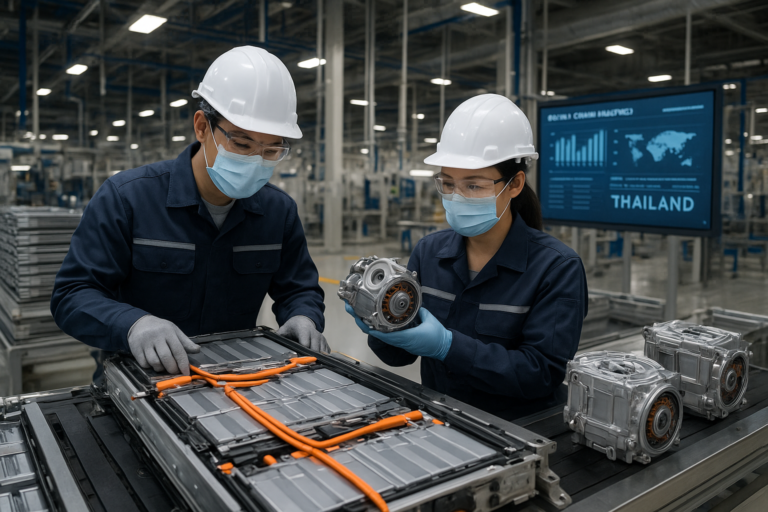
The key signal is that Thailand’s policy focus on electric vehicle (EV) manufacturing supply chains reflects a strategic commitment to anchoring the country as a regional hub in the EV sector’s value chain. This development signals a move beyond assembly-centric capabilities toward integrated supply chain strengthening, which matters profoundly for investors seeking to understand how Thailand is positioning itself in the technology-intensive segments of automotive manufacturing.
This shift matters because it elevates the relative attractiveness of Thai production assets by targeting the supply base expansion and local content improvements, which can influence cost structures and regional export dynamics. For investors, the emergence of Thailand EV manufacturing supply chains as a policy priority underscores the medium-term sectoral transition from conventional automotive to EV-related industries, necessitating recalibration of capital allocation and risk frameworks around evolving automotive ecosystems.
Key Facts
- Thailand’s government has articulated policies designed to develop and support domestic EV manufacturing supply chains.
- The policy framework emphasizes enhancing local content and attracting upstream component manufacturers.
- The initiative includes efforts to integrate battery production and critical EV components within Thailand’s industrial ecosystem.
- Thailand aims to sustain its position as a regional automotive production hub under emerging EV trends.
- Concrete policy implementation details and timelines remain partially unclear from the source content.
Why It Matters
The focus on EV manufacturing supply chains signals a strategic pivot in Thailand’s industrial policy aimed at future-proofing its automotive sector amid global decarbonization trends. Enhancing local supply chains indicates policy intent to move deeper into value-added production, reducing reliance on imported components and strengthening resilience against global supply disruptions. For Thailand, this means increasing the domestic multiplier effect of the EV industry, potentially lifting broader manufacturing productivity and export base quality.
From an investor perspective, the supply chain emphasis influences country risk assessments, corporate strategies, and operational footprints. The creation of integrated EV supply chains can lower input costs and shorten lead times for EV assemblers within Thailand, strengthening competitive positioning compared to other ASEAN economies. Moreover, this could modulate energy import profiles as EV production scales, impacting related sectors.
Investment Implications
Investors with exposure to Thailand’s automotive manufacturing ecosystem should adjust expectations toward firms and sectors aligned with EV supply chain expansion, including battery component makers, electric motor suppliers, and advanced materials providers. Capital allocation strategies may prioritize investments that benefit from policy incentives or are positioned to supply the emerging EV ecosystem.
The emphasis on local content may increase operational complexity and compliance costs for manufacturers in the short term but enhance medium-term cost competitiveness and supply reliability. Additionally, the rise of EV supply chains could shift demand profiles within industrial property and logistics segments due to the need for specialized facilities and distribution networks.
Corporate strategies will also require recalibration to navigate supply chain evolution and tap into government support mechanisms, which can affect valuation models and risk premia for listed companies and private enterprises.
Sector Impact
Positive
- Automotive Manufacturing: Enhanced supply chain localization improves competitiveness and aligns with global EV trends.
- Industrial Components and Materials: Increased demand for battery materials and EV-specific components supports sector growth.
- Logistics and Industrial Real Estate: Expansion of EV supply chains drives demand for specialized industrial facilities and distribution infrastructure.
Neutral
- Energy Sector: Impact depends on the scale of EV production; current implications are limited without detailed data on energy sourcing shifts.
- Financial Services: Current policy signals have indirect effects on credit conditions and capital flows, which remain unclear.
Risk
- Automotive Suppliers: Short-term operational challenges from adjusting to local content requirements and potential supply chain disruptions.
- Policy Implementation Risk: Uncertainty remains on the enforcement and scale of support for supply chain integration, which could limit anticipated benefits.
Strategic Signals
The move to strengthen Thailand EV manufacturing supply chains signals a recognition of the need to integrate vertically and capture greater value within the EV sector’s industrial ecosystem. It reveals Thailand’s intent to position itself beyond a production and assembly base to a technology and component supplier hub in ASEAN. This is indicative of broader economic policy shifts prioritizing industrial upgrading and resilience in strategic sectors.
Second-order effects may include increased demand for skilled labor and downstream technology transfer, which can influence the labor market and education sectors. The policy direction also reinforces Thailand’s competitive stance within ASEAN in automotive and high-tech manufacturing, signaling a nuanced approach to regional industrial leadership amid supply chain realignments.
ASEAN Context
This development appears primarily domestic in nature with limited immediate ASEAN-wide implications.
Risks
Execution risk is significant due to complexities in upgrading supply chains and aligning stakeholders behind local content requirements. Without clear implementation pathways or timely incentives, supplier engagement may lag, which would dilute policy impact. Additionally, external risks such as global supply chain disruptions and competitor moves within ASEAN could affect Thailand’s ability to capture the intended value-add.
Market risks include potential cost inflation for manufacturers during transition periods, which may weigh on margins. Policy uncertainty surrounding the scope and enforcement timing could also complicate capital planning for both domestic and foreign investors.
Bottom Line
Thailand’s policy targeting EV manufacturing supply chains is a critical signal of industrial upgrading focused on capturing more value in the EV sector. This affects Thailand’s automotive-related sectors and industrial suppliers, shaping investment dynamics and competitive positioning. The initiative embodies strategic aspirations to deepen domestic content and resilience but carries execution uncertainties that investors must factor into risk assessments. Ultimately, the signal points to Thailand’s evolving role as a more integrated EV production hub within ASEAN’s economic landscape.
Thailand Investor Brief
Stay Ahead of Thailand and ASEAN Markets
Explore Thailand Signal Capital’s flagship investor intelligence service,
including free market insights and premium daily briefings for investors,
executives, entrepreneurs, and ASEAN-focused professionals.
- Thailand and ASEAN market intelligence
- Investment implications and strategic signals
- FREE and PRO briefing options
Frequently Asked Questions
Why does this development matter for Thailand investors?
This development matters because it may affect Thailand’s investment
environment through policy direction, sector exposure, trade dynamics,
capital allocation, or ASEAN market positioning.
Which sectors could be affected?
The most relevant sectors depend on the specific development, but investors
should assess exposure across policy-sensitive industries, financial
services, trade-linked sectors, infrastructure, property, tourism, energy,
and ASEAN-facing businesses.
How does this affect Thailand’s position in ASEAN?
The ASEAN impact depends on whether the development changes regional
competitiveness, cross-border investment, supply chains, or investor
sentiment. Thailand’s role should be assessed relative to nearby markets
such as Singapore, Malaysia, Vietnam, Indonesia, and Cambodia.
What should investors watch next?
Investors should watch implementation details, policy follow-through,
sector-level responses, corporate earnings signals, regulatory changes,
and whether the development creates measurable shifts in demand, costs,
or capital flows.
Complete Guide
For a broader investment framework, continue with the Thailand Tourism Investment Guide 2026.